Empty nester renovation financing can help homeowners adapt their homes after their children move out without taking more money from retirement accounts than necessary. The right approach depends on the renovation budget, available home equity, income, tax situation, borrowing costs, and how much cash needs to remain available for retirement.
When children leave home, spare bedrooms may sit unused while bathrooms, kitchens, and hallways no longer suit the household’s changing needs. Some homeowners want to convert a bedroom into an office, update a bathroom for easier access, or make the house more comfortable for the years ahead.
The main financial question is how to pay for these changes without weakening long-term retirement security. Withdrawing from retirement savings is one option, but home equity, personal loans, available cash flow, and a phased renovation plan may also be worth comparing.
Why Retirement Withdrawals Can Cost More Than Expected
A renovation funded from a traditional 401(k) or traditional IRA may cost more than the amount withdrawn suggests. These withdrawals are generally subject to ordinary federal income tax and may also be subject to state income tax. Depending on the account holder’s age and circumstances, an additional early-withdrawal penalty may apply.
For example, a $60,000 withdrawal does not necessarily provide $60,000 to spend on a renovation after taxes. The actual amount available depends on the household’s taxable income, filing status, applicable tax rates, and other circumstances. A large withdrawal can also affect the taxation of Social Security benefits and, for some Medicare beneficiaries, future income-related premium adjustments.
There is also an opportunity cost. Money removed from an investment account can no longer generate potential returns within that account. If the withdrawal happens during a market downturn, selling investments may lock in losses that a longer investment horizon could otherwise have allowed time to recover from.
This does not mean retirement funds should never be used for home improvements. It means the withdrawal should be evaluated against the potential cost of borrowing, the household’s expected expenses, and the need to maintain a reserve for healthcare and everyday living.
Home equity may provide another funding source, but borrowing against a property carries its own risks. The loan must be repaid, interest adds to the total project cost, and the home may be at risk if the borrower cannot meet the repayment terms.
Which Renovation Financing Options Should Empty Nesters Compare?
Renovation budgets vary according to the size of the project, materials, labor, and the condition of the existing home. Instead of relying on a single estimated cost, obtain written bids and compare financing options using the amount actually needed.
| Financing option | When it may fit | Main considerations |
|---|---|---|
| Home equity line of credit (HELOC) | Work completed in stages or projects with uncertain final costs | Usually variable interest rates, draw-period limits, and potentially higher payments later |
| Home equity loan | A defined project with a known budget | Fixed payments may be available, but closing costs and home-secured debt still matter |
| Cash-out refinance | Situations where replacing the existing mortgage is financially advantageous | New loan terms and closing costs; replacing a low-rate mortgage may increase borrowing costs |
| Personal loan | Smaller projects or homeowners who prefer not to use home equity | Rates may be higher, repayment terms shorter, and monthly payments larger |
| Contractor financing | Projects where a contractor offers a financing arrangement | Promotional periods, fees, deferred interest, and repayment deadlines require careful review |
| Cash flow and phased work | Homeowners with sufficient income or savings available outside retirement accounts | Work may take longer, but avoiding a loan can reduce interest costs |
A HELOC can provide flexibility when renovation work is divided into several stages because borrowers generally pay interest on the amount drawn rather than the entire credit limit. However, rates can change, and repayment terms may become less favorable after the draw period ends.
A home equity loan may be more predictable when the total cost is known and a fixed interest rate is available. Both options use home equity as collateral, so compare the monthly payment, fees, repayment period, and consequences of missed payments.
Cash-out refinancing deserves particular scrutiny if the existing mortgage has a low interest rate. Replacing that mortgage may increase the cost of the entire outstanding balance, not just the money needed for renovations. A second loan is not automatically cheaper, so compare the total cost of both arrangements.
Contractor financing also requires a close look at the agreement. A low introductory payment may not reflect the regular payment after a promotional period, and some offers have conditions that can trigger deferred interest.
How Can Phased Renovations Keep Costs Under Control?
Completing every improvement at once can make it harder to monitor spending and respond to unexpected repairs. A phased plan lets homeowners address immediate needs first and postpone less important work until the budget allows.
Before starting, review the scope, timeline, and contingency allowance. A written project plan and a realistic renovation budget can help prevent upgrades from expanding beyond the original priorities.
1. Start With the Primary Bathroom
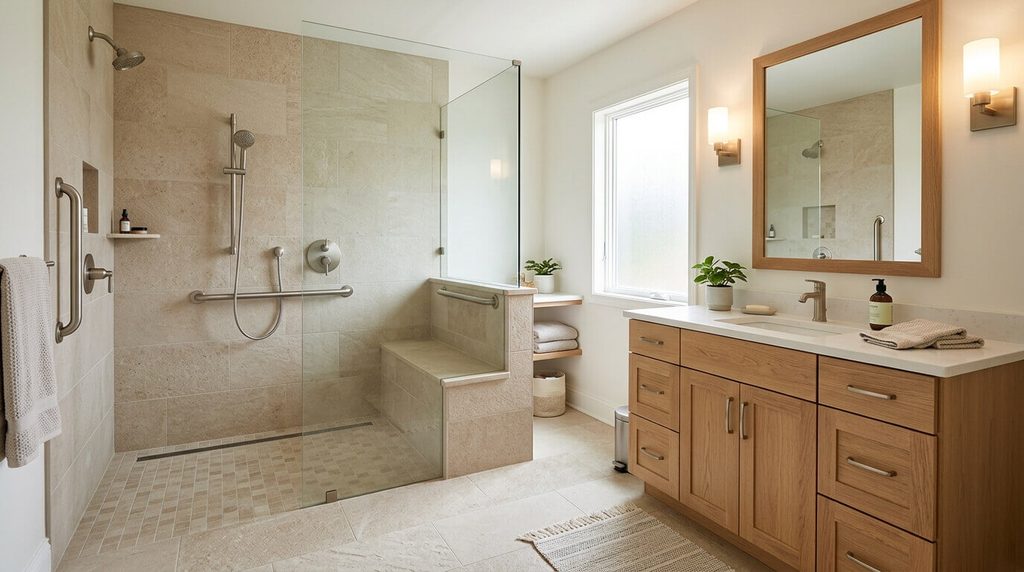
The primary bathroom may deserve attention if the existing layout makes everyday routines difficult. A bathtub that is hard to step over, slippery flooring, limited lighting, or inadequate support can become more important as household needs change.
Possible improvements include a curbless shower, slip-resistant flooring, better lighting, accessible controls, and reinforcement for grab bars. The best choices depend on the bathroom layout, the occupants’ needs, and the cost of plumbing or structural changes.
Review accessible bathroom modifications before deciding which features belong in the project. Planning accessibility improvements during a renovation may reduce the need for disruptive changes later, although costs depend on the home’s existing conditions.
If a household member is a veteran with qualifying medical needs, certain home modifications may be eligible for assistance through the Department of Veterans Affairs. The Home Improvements and Structural Alterations (HISA) program has eligibility rules and benefit limits that should be checked directly with the VA before budgeting around an expected payment.
2. Check Eligibility for Home Modification Grants
Some veterans with qualifying service-connected disabilities may be eligible for Specially Adapted Housing (SAH) or Special Housing Adaptation (SHA) grants. These programs have distinct eligibility requirements, permitted uses, and benefit limits that can change over time.
A VA bathroom remodel guide may provide a starting point for understanding bathroom safety changes, but it should not replace current VA guidance.
Before work begins, confirm whether the proposed modification qualifies, which documentation is required, whether prior approval is necessary, and how payment is handled. Do not assume that an expense will be reimbursed after the renovation is complete.
3. Convert an Unused Bedroom
An empty bedroom may need only modest changes to serve a new purpose. Depending on the household’s needs, it could become a home office, hobby room, exercise area, or guest bedroom.
Start by evaluating lighting, storage, flooring, electrical outlets, and furniture placement. Cosmetic improvements may be sufficient if the room is already in good condition. Avoid major structural changes unless they provide a clear practical benefit.
4. Schedule Kitchen and Exterior Work Later
Kitchen remodeling and major exterior improvements can involve substantial material and labor costs. If these projects are not urgent, postponing them may make it easier to maintain an emergency reserve and pay down existing renovation debt.
Review the expected scope and possible hidden repairs before committing to the next phase. The home renovation planning process can help identify decisions involving layout, permits, materials, scheduling, and contractor coordination.
Which Investment Accounts Should You Consider Before Borrowing?
Borrowing is not always the least expensive option. Interest rates, loan fees, tax consequences, and the household’s remaining investment assets all influence the decision.
If using investments is under consideration, review the accounts separately rather than treating every dollar as equally accessible.
- Taxable brokerage account: Selling investments may create capital gains or losses. Tax is generally based on the gain rather than the full sale proceeds, although the final result depends on the investment’s cost basis, holding period, and tax circumstances.
- Roth IRA contributions: Regular Roth IRA contributions can generally be withdrawn without tax or penalty, but conversions, earnings, account age, and distribution rules can affect the treatment of other withdrawals. Roth 401(k) rules are different, so check the specific account.
- Traditional IRA or 401(k): Withdrawals are generally taxable as ordinary income, and additional rules may apply depending on age and account circumstances. Required minimum distributions can also affect retirement income planning.
- Health savings account (HSA): HSA funds have special tax advantages for qualified medical expenses. Using them for a nonqualified renovation expense can trigger income tax and, in some cases, an additional penalty. Preserving the account for eligible healthcare costs may be useful, but the decision depends on the household’s medical expenses and available resources.
These are general considerations, not a universal order for spending investments. A tax professional or fiduciary financial planner can help compare the effects of a withdrawal with the long-term cost of borrowing.
How Can You Decide Whether to Borrow or Pay Cash?
Start by obtaining a written contractor bid that identifies the work included, materials, labor, payment schedule, and likely exclusions. Ask about permits, potential structural or plumbing issues, and how changes to the scope will be priced.
Next, determine how much of the project can be paid from cash without reducing the emergency fund or leaving too little for routine retirement expenses. Available home equity should not be treated as a spending target simply because a lender is willing to extend credit.
Then compare the alternatives using the same project cost and repayment period. Include loan interest, fees, closing costs, potential tax effects, and the value of keeping investments in place. For a retirement-account withdrawal, estimate the amount that would need to be withdrawn to cover the project’s net cost after taxes.
Finally, test the budget against less favorable circumstances. Could the household still afford the payment if expenses rose, investment values fell, or income changed? Would the renovation leave enough accessible money for healthcare, home maintenance, and unexpected bills?
The most suitable financing plan is the one that balances the home’s practical needs with the household’s ability to meet future expenses. For some homeowners, that may mean borrowing against equity. For others, using available cash, withdrawing a carefully chosen amount from investments, or completing the work in stages may be more appropriate.
A renovation can make a home more comfortable for the next phase of life, but its cost should fit within a retirement plan rather than determine how that plan has to change.